The right health insurance doesn't just pay hospital bills. It protects years of financial discipline.
We spend years building our financial future. We invest for our children's education, plan for retirement, build emergency funds, and work hard to create wealth that gives our family security and peace of mind.
But there is one question that every family should ask before focusing on growing wealth.
"If a medical emergency strikes tomorrow, will our savings continue working towards our goals, or will they be diverted to meet hospital expenses?"
Most people believe the answer lies in having a health insurance policy.
After interacting with numerous families over the years, we have realized that the better question is:
"Do I have the right health insurance?"
The difference between these two questions can significantly influence a family's financial future.
Company Health Insurance Is Valuable... But Is It Enough?
A person once asked us, "Why should I buy a personal health insurance policy when my employer already provides one?"
It was a fair question. Unfortunately, a few years later, he was diagnosed with cancer.
The treatment was extensive and the total medical expenses were close to ?35 lakh. His employer's health insurance covered ?5 lakh, leaving the family to arrange the balance through savings, support from family and other financial resources.
The employer had fulfilled its commitment. The policy had worked exactly as designed.
The lesson, however, was clear.
Corporate health insurance is an employee benefit. Personal health insurance is a family's long-term financial protection.
Your employment may change. Your health risks don't.
Don't Wait Until You Need Health Insurance
Another common belief is, "I'm healthy today. I'll buy health insurance later."
While this sounds practical, health insurance is one of the few financial products that is easiest to purchase when you are healthy.
If someone develops diabetes, hypertension, a heart condition or another medical illness before buying a policy, the experience can be very different.
Depending on the insurer's underwriting guidelines, the proposal may be accepted on standard terms, accepted with an additional premium (loading), carry waiting periods or specific exclusions, or in some cases may not be accepted.
Every insurer follows its own underwriting process, so the outcome varies. The important lesson is simple.
The best time to buy health insurance is when you don't need it—not when you do. Having Health Insurance Doesn't Always Mean Every Expense Is Covered
Many families assume that if they have a health insurance policy, every hospital bill will automatically be reimbursed. Unfortunately, it doesn't always work that way.
One person underwent treatment for kidney stones and relied on his employer's health insurance. While a substantial part of the expenses was covered, certain costs had to be borne personally because they were either outside the policy coverage or subject to policy limits.
In another instance, a family that had maintained a personal health insurance policy for several years expected the insurer to settle the entire claim. Only after the claim was processed did they realise that policy conditions such as co-payment and other applicable limits meant they received only around 60% of the admissible expenses.
Neither policy had failed.
The families simply hadn't understood how their policies worked.
Health insurance should never be purchased solely on the basis of premium or sum insured. Understanding the policy is just as important as owning one.
Choosing the Right Policy Is About Asking the Right Questions
When people compare health insurance, the first comparison is usually the premium. In reality, the better comparison is the protection the policy provides.
Before buying or reviewing a health insurance policy, consider asking:
• Am I relying only on my employer's health insurance?
• Is my current sum insured adequate considering today's healthcare costs?
• Do I understand important policy conditions such as waiting periods, co-payment, exclusions and room eligibility?
• If my health changes tomorrow, will buying a new policy be as easy as it is today?
• When was the last time I reviewed my health insurance?
Often, the quality of the questions determines the quality of the financial decision.
Health Insurance Needs Regular Review
Life keeps changing.
You get married.
Your family grows.
Your income increases.
Your parents grow older.
Healthcare costs continue to rise.
Yet many people continue with the same policy they purchased years ago without reviewing whether it still meets their family's needs.
Just as we review our investment portfolio periodically, our health insurance deserves the same attention.
A review doesn't always mean changing the policy. Sometimes it simply means understanding it better.
Health Insurance Review Checklist
Take a few minutes to review your family's current protection.
Your Coverage
? Do I have a personal health insurance policy in addition to my employer's cover?
? Is my sum insured sufficient considering today's medical costs?
? Have I increased my cover as my responsibilities have grown?
Understanding Your Policy
? Do I know the waiting periods applicable to my policy?
? Am I aware of any co-payment or deductible?
? Do I understand the major exclusions and policy limits?
? Does my policy offer restoration of the sum insured?
My Family
? Have I reviewed my policy after major life events such as marriage or the birth of a child?
? Have I planned separately for my parents' healthcare needs?
Claim Preparedness
? Does my family know where the policy documents are kept?
? Do I know the cashless claim process and nearby network hospitals?
Annual Review
? Have I reviewed my policy within the last 12 months?
? Am I confident that my policy still meets my family's current needs?
If you answered "No" or "I'm Not Sure" to several of these questions, it may be time for a review—not necessarily to buy a new policy, but to ensure that your existing protection is aligned with your family's present and future needs.
A Final Thought
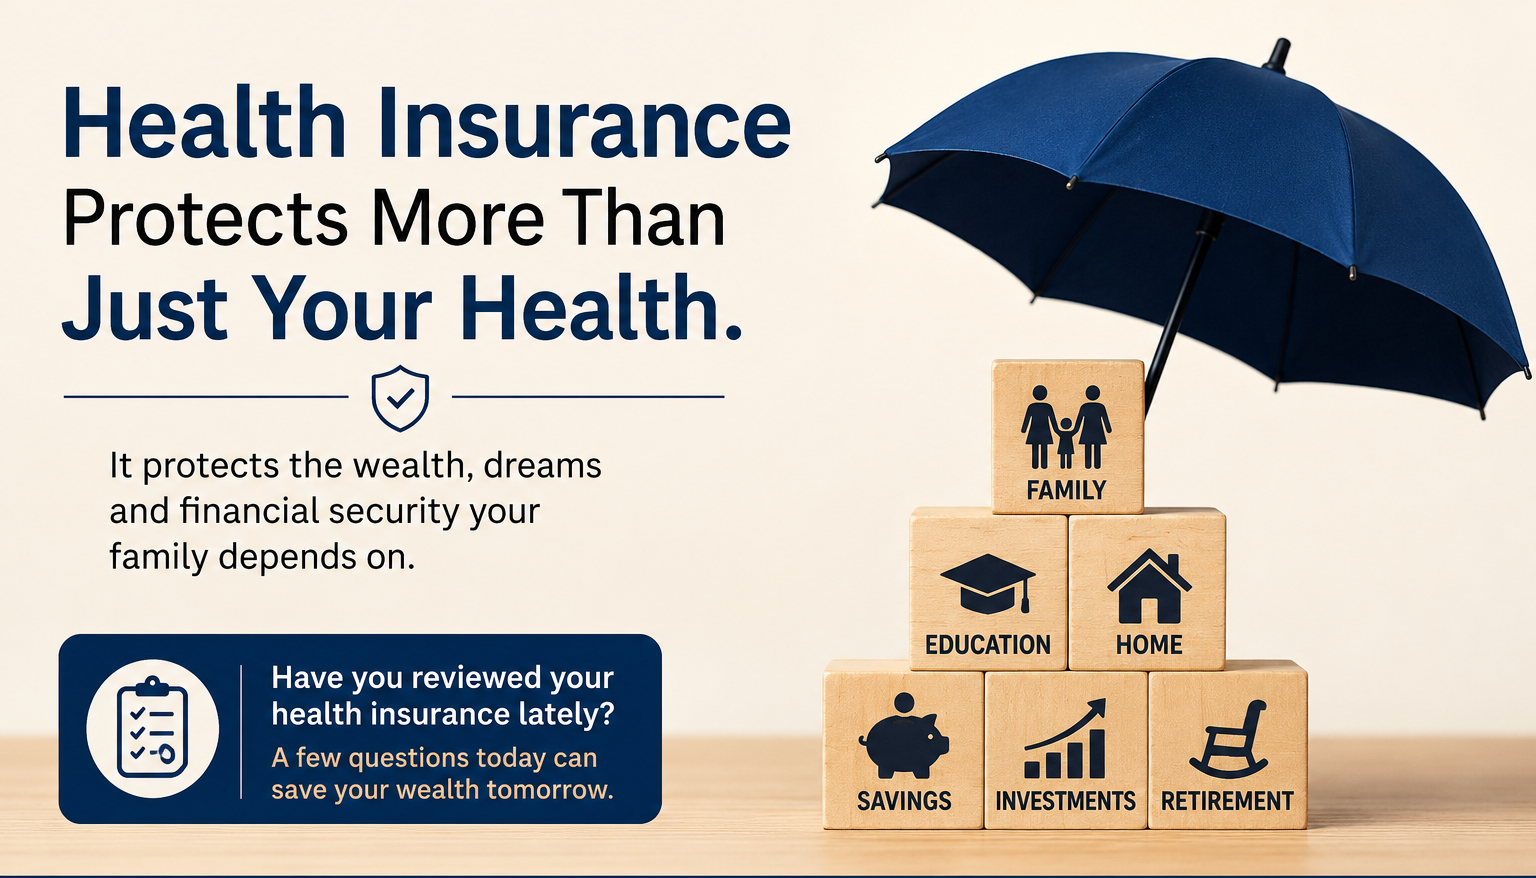
Health insurance is often seen as an expense. In reality, it is one of the most important financial safeguards a family can have.
Its purpose is not only to pay hospital bills. Its real purpose is to ensure that your retirement corpus remains untouched, your child's education fund stays intact, and years of disciplined investing are not disrupted by an unexpected medical emergency.
Before you invest another rupee in creating wealth, pause for a moment and ask yourself one simple question:
"Have I done enough to protect the wealth my family has already built?"
That single question may prove to be one of the most important financial decisions you ever make.
Related Articles