A real-life perspective on Paper Wealth vs Guaranteed Comfort
Most financial advice sounds logical… until real life happens.
Let me share a simplified story of two families—both disciplined, both responsible—but with very different approaches to building wealth.
The Starting Point
In 2012, two individuals—Raj and Amit—both aged 35, started planning seriously for their future.
Their goals were identical:
• Children’s education
• Retirement at 60
• Financial security for family
Their monthly investable surplus: ?50,000
Family 1: Raj – The Comfort of Guarantees
Raj believed in certainty.
He allocated most of his savings into:
• Traditional insurance plans
• Guaranteed return products
• Fixed income instruments
His thought process was simple:
? “At least I know what I will get.”
Family 2: Amit – The Discipline of Growth
Amit took a different route.
He structured his finances into:
• Equity mutual funds (for long-term goals)
• Term insurance (for protection)
• Emergency fund (for stability)
His belief:
? “Short-term volatility is okay, long-term growth is essential.”
Fast Forward to 2020: The Market Crash
When markets corrected sharply:
• Raj felt reassured—his portfolio showed no visible drop
• Amit saw his portfolio fall by nearly 25%
At that moment:
? Raj felt smart
? Amit felt uncomfortable
This is where most investors change strategy.
But Amit didn’t.
Fast Forward to 2025: Reality Sets In
Markets recovered. Growth resumed.
Here’s what their portfolios looked like:
Raj (Guaranteed Path)
• Stable, predictable value
• Returns in the range of 5–6%
• Struggling to beat inflation
• Future goals becoming tighter
Amit (Growth + Protection Approach)
• Portfolio recovered and grew significantly
• Returns averaging 10–12% over the long term
• Goals back on track—and ahead
The Real Difference Was Not Returns
It was strategy clarity.
Raj optimized for:
? Comfort today
Amit optimized for:
? Security tomorrow
Where Protection Actually Matters
Now here’s the important part—this is not about rejecting guarantees.
Let’s say something unfortunate happened to both families.
• Raj’s policies would provide a payout
• Amit’s term insurance would provide a much larger payout at a fraction of the cost
? In both cases, protection exists.
But only one strategy allowed wealth to grow meaningfully alongside protection.
The Insight Most Investors Miss
Guaranteed products solve for:
? Predictability
But they often compromise:
? Growth
? Inflation-beating returns
? Long-term wealth creation
The Real Purpose of Paper Wealth
Paper wealth is often misunderstood because it fluctuates.
But in reality, it is:
? The only asset class that has the potential to consistently outpace inflation and build real wealth over time
Yes, it moves. But it also grows.
So What Should an Ideal Strategy Look Like?
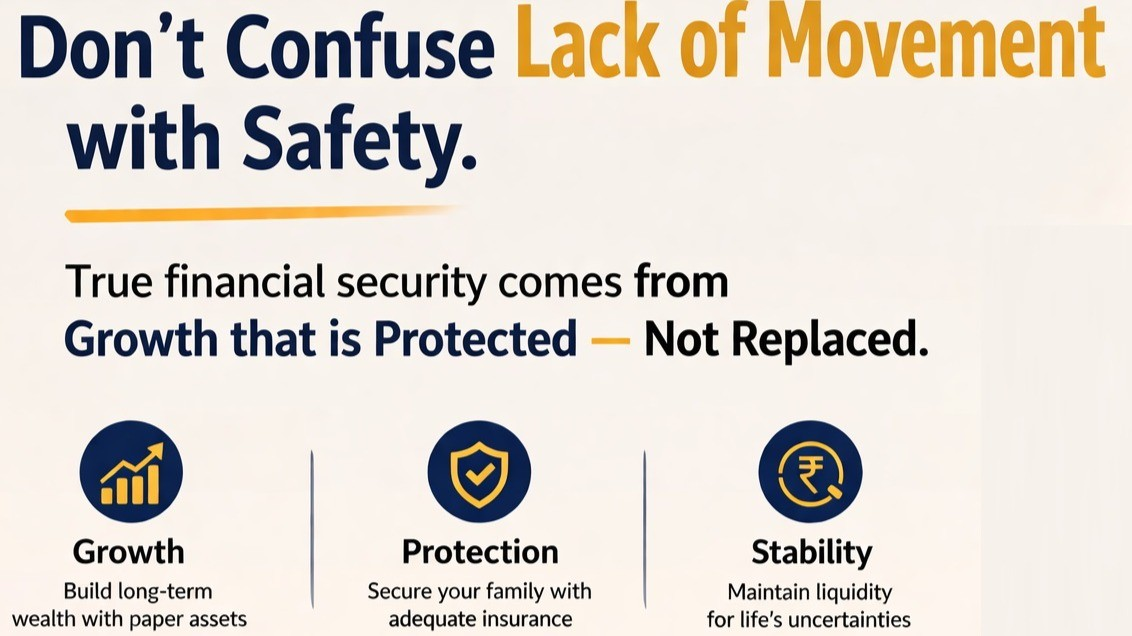
A strong financial plan is not about choosing one over the other.
It is about balance:
• Growth (Paper Wealth) ? For long-term goals
• Protection (Insurance) ? For life’s uncertainties
• Liquidity (Emergency funds) ? For stability
Final Thought
Both Raj and Amit were responsible.
Both cared about their families.
But only one built a plan that could withstand time, inflation, and uncertainty together.
“Don’t confuse lack of movement with safety. True financial security comes from growth that is protected—not replaced.”
Related Articles